 56 minutes ago
Shares of Mahindra & Mahindra (M&M) were trading in the red on Wednesday, October 14, as investment banking firm Kotak Institutional Equities reduced it's target price to ₹4,000 from ₹4,175 earlier, while maintaining its "Buy" rating on the stock.
Even after the price target cut, Kotak expects an upside potential of up to 40% for Mahindra & Mahindra's shares, when compared to the stock's closing price on Tuesday.
The firm said M&M’s stock has corrected over the past year amid concerns over a tractor downcycle, market share losses in sports utility vehicles (SUVs), competition from new entrants and commodity inflation. However, it believes these concerns are largely cyclical or reversible.
Kotak attributed the slowdown in tractors to a weak monsoon and a high base, rather than any structural change in the drivers of farm mechanisation. It also expects new launches based on the NU_IQ platform from the first half of calendar year 2027 to help the automaker recover some of its lost SUV market share.
The firm said M&M’s pricing power, supported by its strong position in the SUV market, should help it deliver a margin recovery. At current levels, the stock implies the company's volumes to grow at a compound annual growth rate (CAGR) of just 3.5% through FY2050, which Kotak considers conservative. The stock is trading at around 15.5 times estimated core earnings per share for FY2028, which the firm considers inexpensive.
M&M's September performance and growth outlook
M&M reported a 19.2% year-on-year increase in total production to 1.22 lakh units in September, compared with 1.02 lakh units a year earlier. Total sales rose 16.3% to 1.14 lakh units from 97,744 units, while exports increased 9.2% to 4,458 units.
Earlier this month, the company reiterated its growth outlook for SUVs and light commercial vehicles (LCVs), while flagging a moderation in tractor industry growth.
Rajesh Jejurikar, Executive Director and CEO of M&M’s Auto and Farm sectors, said the company remained on track to meet its earlier growth expectations.
M&M expects the tractor industry to grow around 5% in FY27, reflecting a higher base after strong growth in the previous year, delayed monsoon conditions and pressure on reservoir levels.
M&M analyst consensus and stock reaction
Of the 41 analysts tracking the stock, 38 have "Buy" recommendations and three have "Hold" ratings on M&M, with no "Sell" recommendations.
The average 12-month target price is ₹4,109.74, implying an upside of approximately 44% from Tuesday’s close of ₹2,864.40.
M&M is also one of Nomura's top picks among original equipment manufacturers (OEMs), based on the rising EV penetration theme. The global investment firm has a Buy rating on the stock.
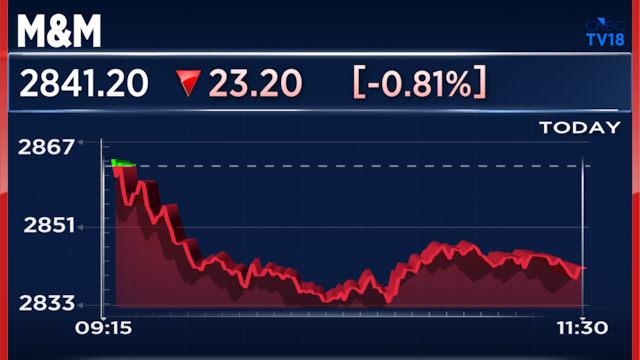
Shares of auto manufacturer were trading almost 1% lower on Wednesday around 2,837.80. The stock has declined about 25% so far in 2026 and 18% in the trailing 12-month period.